
Emerging Coast — Investment Thesis
The Texas
Megaregion
As Texas Grows, Its Major Metros Are Coalescing into a Megaregion.
For generations, America's traditional coasts dominated the nation's economic growth. Today, that balance is shifting. In 2026, Texas surpassed California as the state with the most Fortune 500 headquarters in the nation. As population growth slows in California and New York, companies, capital, and people are flooding into Texas, which has quickly become the Emerging Coast.
From 2010 to 2020, the four major metros anchoring the Texas Megaregion — Dallas–Ft Worth, Austin, San Antonio and Houston — absorbed most of this historic growth, including nearly nine of every ten new Texans, making it the fastest-growing megaregion in the country.
Early in this cycle, growth was concentrated in and around the megaregion's major metro areas, but since 2020 it has increasingly spilled outward into the surrounding exurban land and satellite towns.
The Megaregion at a Glance
Nearly 23 million people, and adding millions more.
The Thesis
The Rise of the Exurbs
For a century, people's lives have largely been tied to proximity to cities. That dependence is rapidly eroding. Remote work, same-day delivery, satellite internet, and telehealth have loosened the tie between where people work and live. This isn't a temporary cycle. It's a structural shift that driverless cars, drone delivery, and AI will further accelerate.
And Texas is at the epicenter of this shift. The Census Bureau's 2025 estimates show that four of the nation's ten fastest-growing counties by percentage ring Texas Megaregion cities: Waller, Kaufman, Liberty, and Caldwell. In the same period, Dallas and four established suburbs — Arlington, Plano, Irving, and Garland — lost population.
As growth moves outward from urban cores and established suburbs, satellite towns and rural areas in the exurbs are seeing a renaissance.
Instead of buying in the urban cores, where prices have already run, we acquire land in the exurban counties absorbing that growth — where populations are rising and land prices have yet to catch up.
That gap between growth and land values is our strategic focus.
The Region
The Texas Megaregion
Percent change in county population, 2010–2025. Texas added 6.6 million residents over that span, and 93% of that growth landed in the Texas Megaregion.
Source: U.S. Census Bureau, 2010 Census (April 1, 2010) and Vintage 2025 Population Estimates (July 1, 2025). Growth share is net population change. Texas Triangle: the 66-county region defined by the University of Texas at Austin. Map: Emerging Coast.
Structural Advantage
Why Texas
Texas has six advantages, compounding at once.
Time-Lapsed Growth Corridor Development
Texas Megaregion
2010 – Present
The growth reshaping the Texas Megaregion isn't just a projection. Across the expanding edges of Dallas–Fort Worth, Houston, Austin, and San Antonio, once-rural land is transforming into suburbs, commercial centers, and satellite communities. The transformation is already visible—and accelerating.
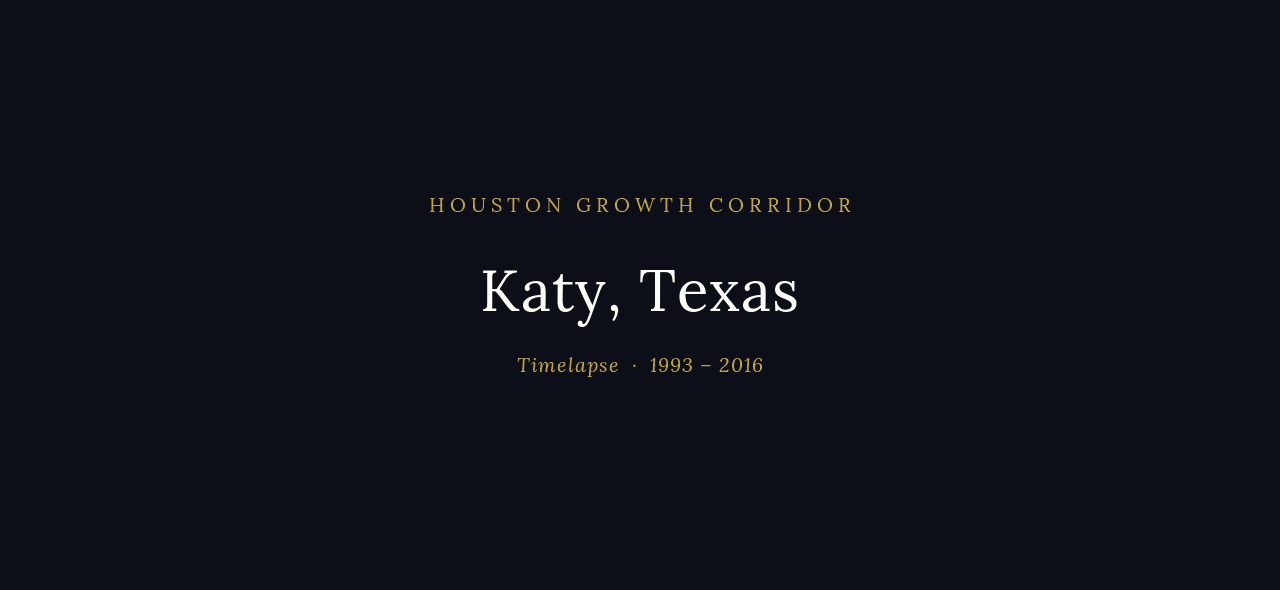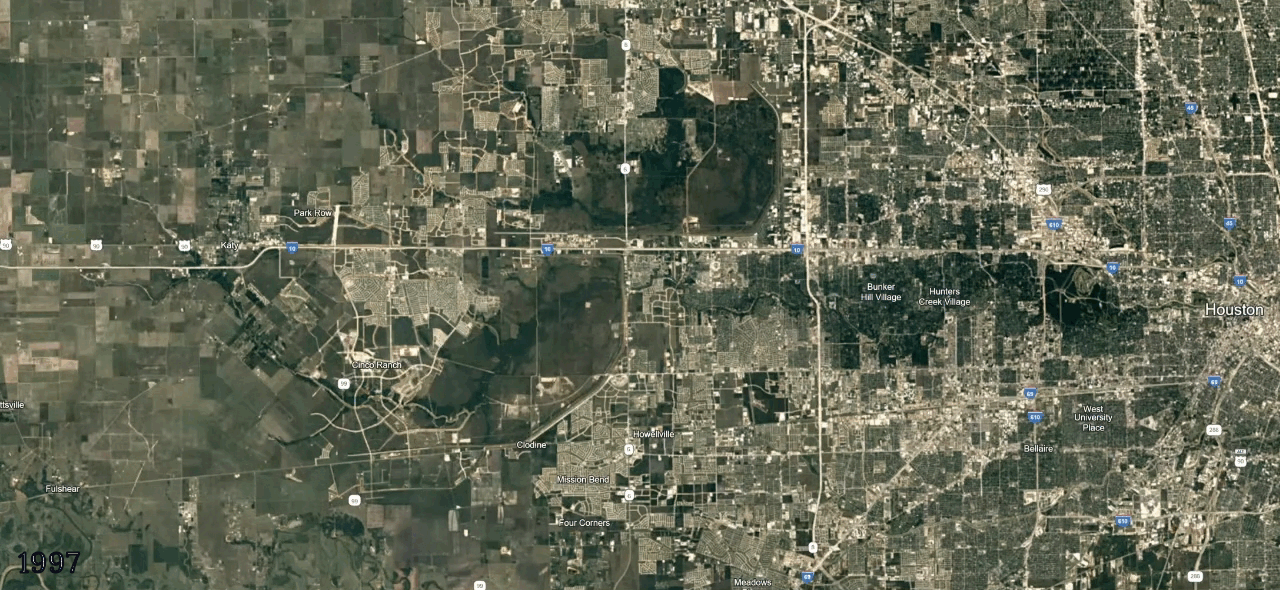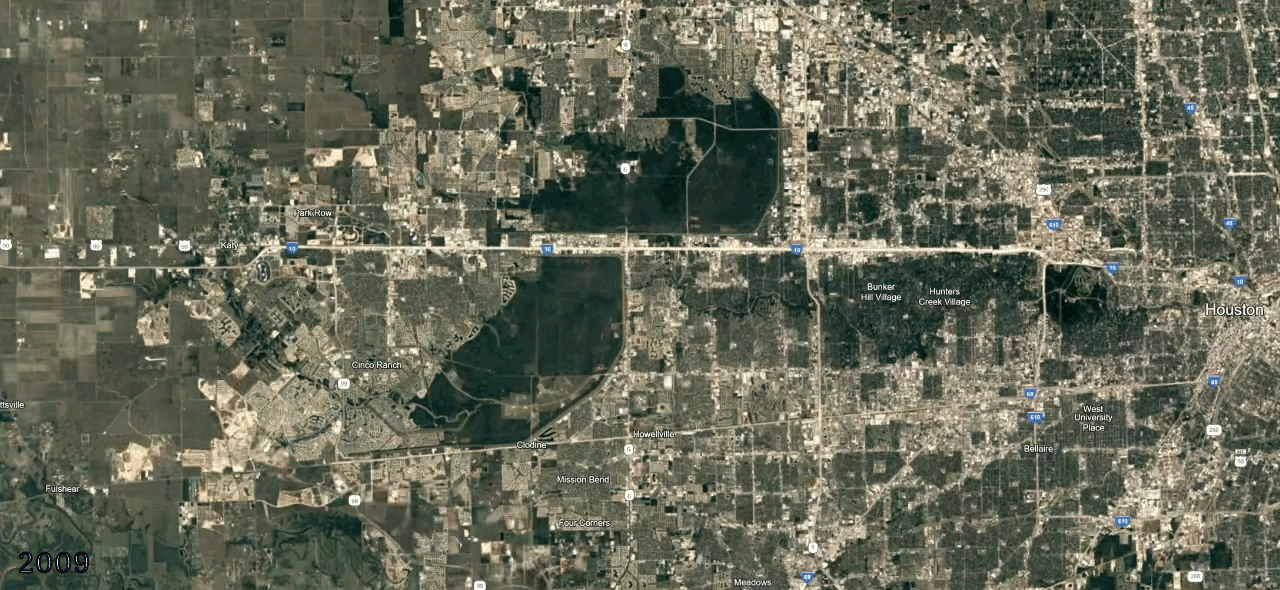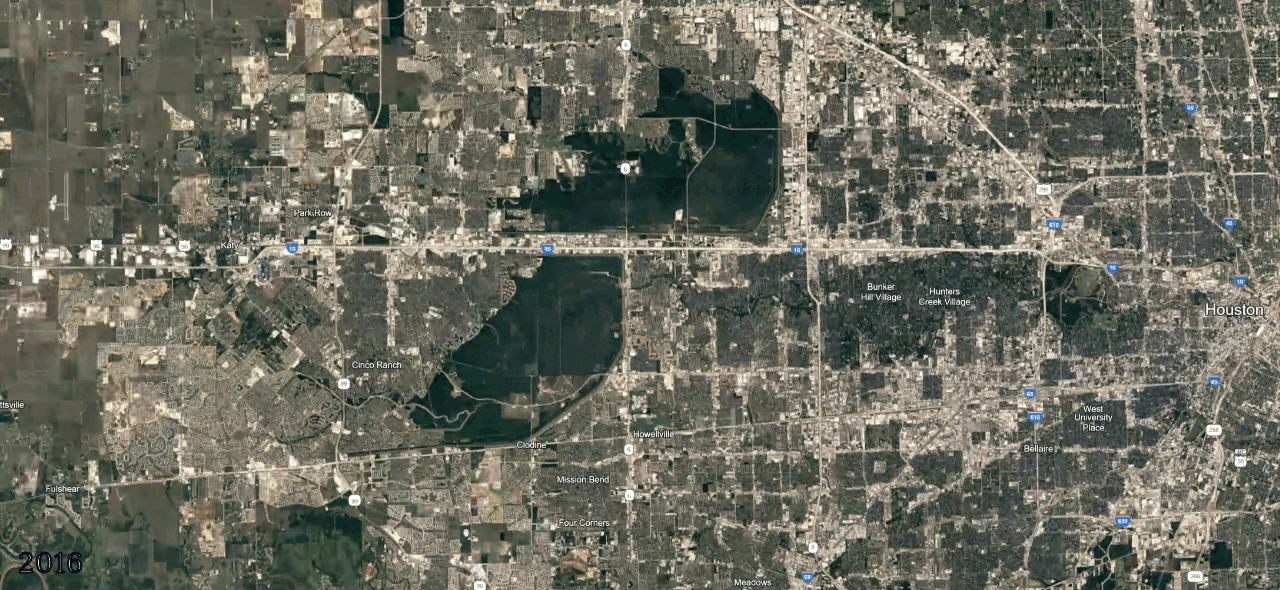
Texas Megaregion — West Houston / Katy Corridor
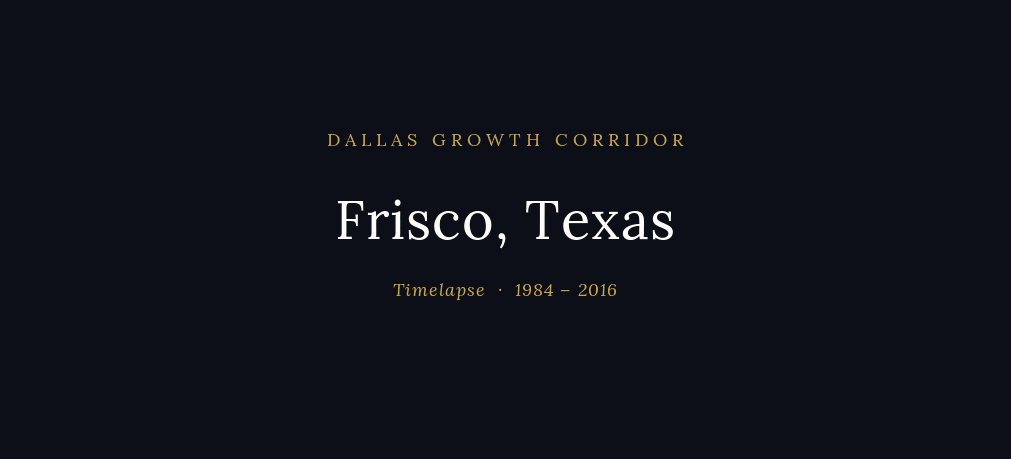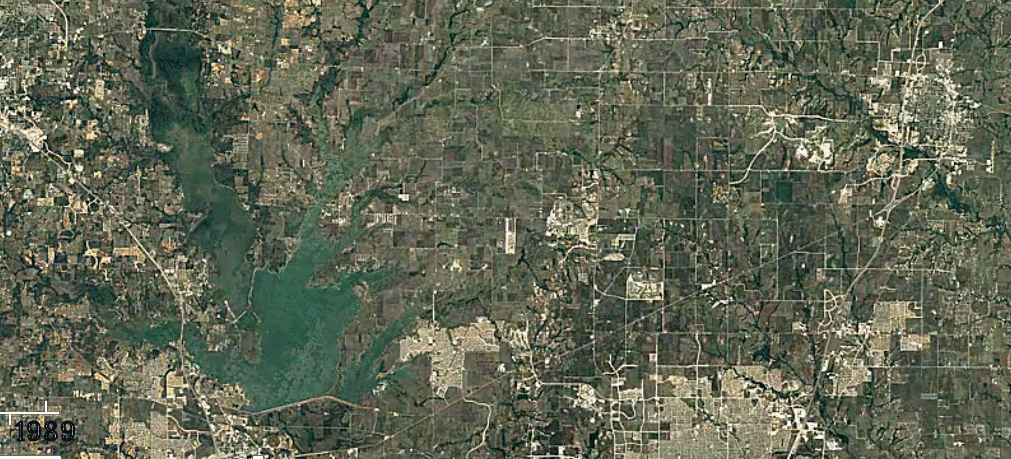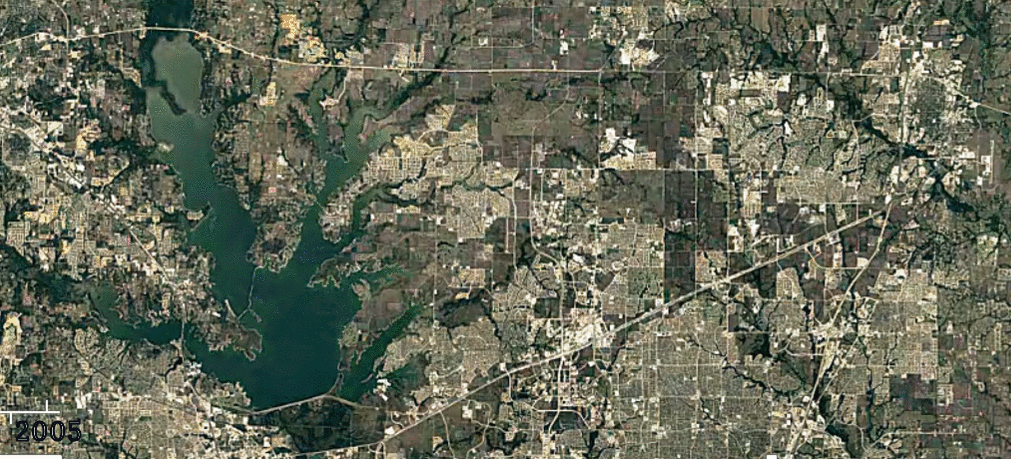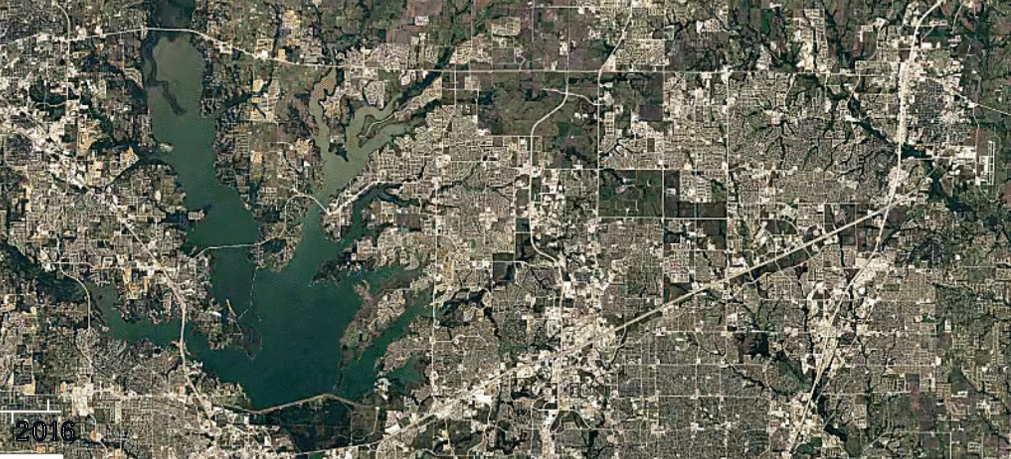
Texas Megaregion — Frisco, TX (1984–2016)
Historical Context
This Has Happened Before
Texas is following a pattern that played out decades earlier along the East and West Coasts. As major metropolitan regions expanded, development pushed outward into surrounding growth corridors. Farmland became suburbs and exurbs, land values rose, and early investment opportunities gave way to mature, increasingly expensive markets.
The Boston–Washington corridor absorbed post-industrial restructuring. Land between the cities in New Jersey, Connecticut, and Maryland moved from farmland to suburb to exurb.
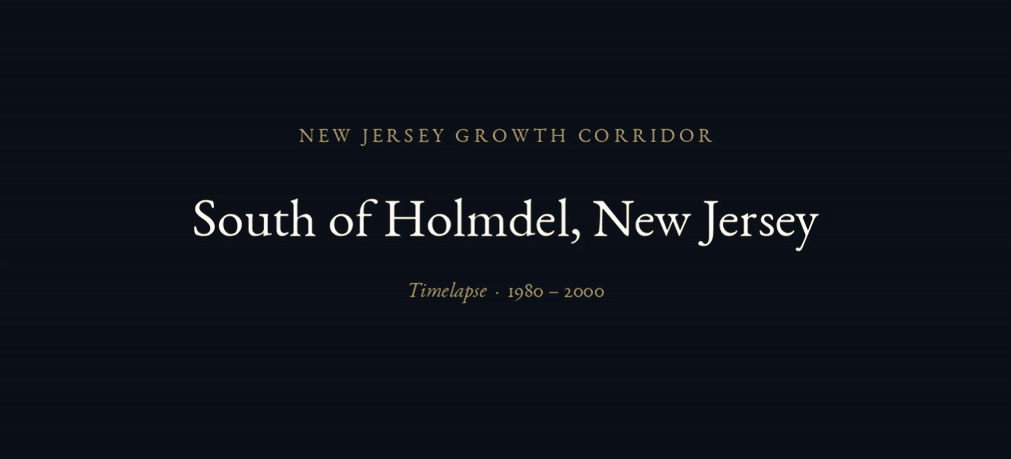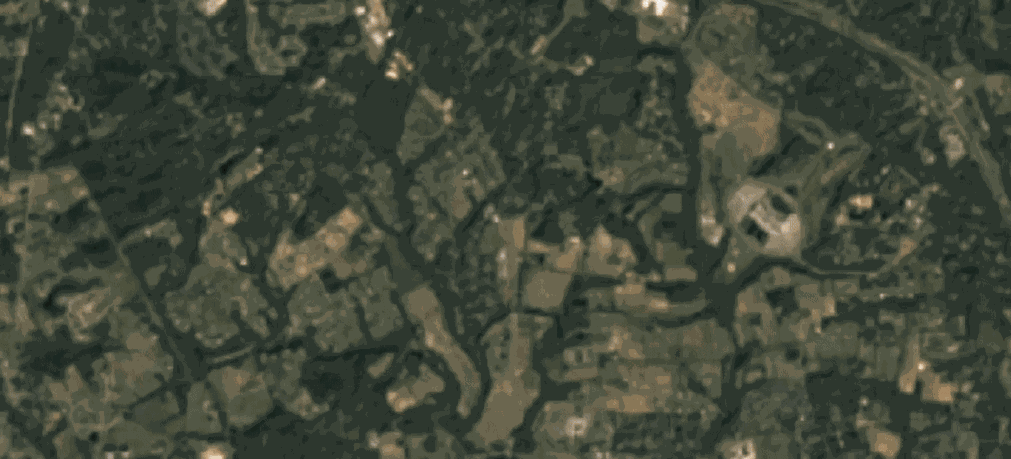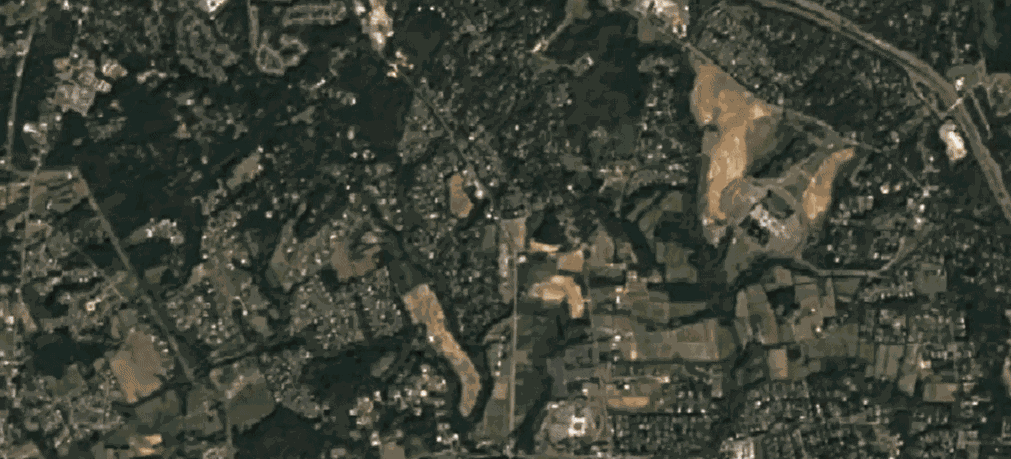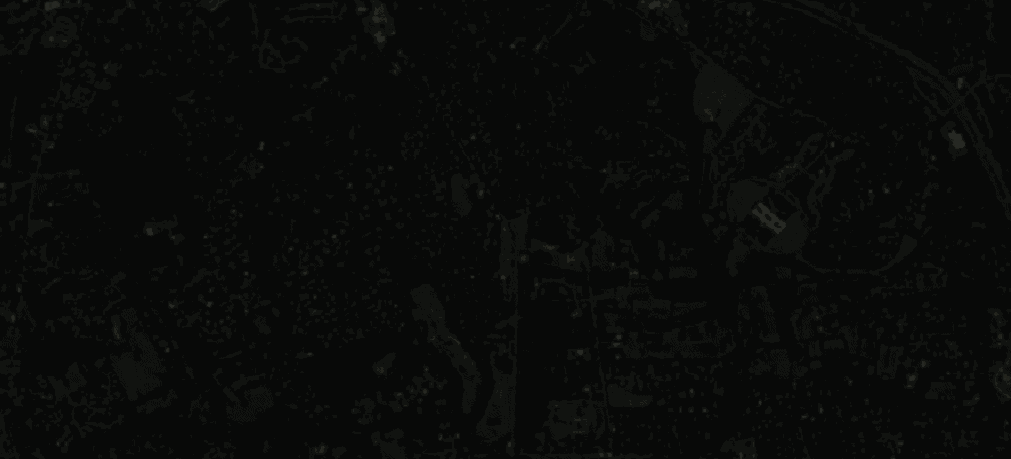
East Coast — Holmdel, NJ
The Pacific megaregion, Los Angeles to San Diego and San Francisco to Sacramento, compressed geography and drove up prices. Land in the growth path was repriced first.
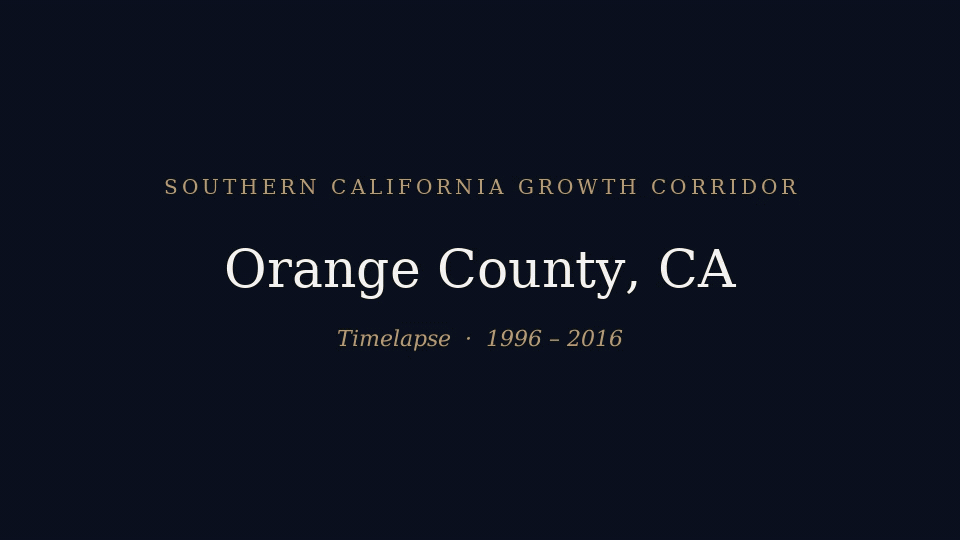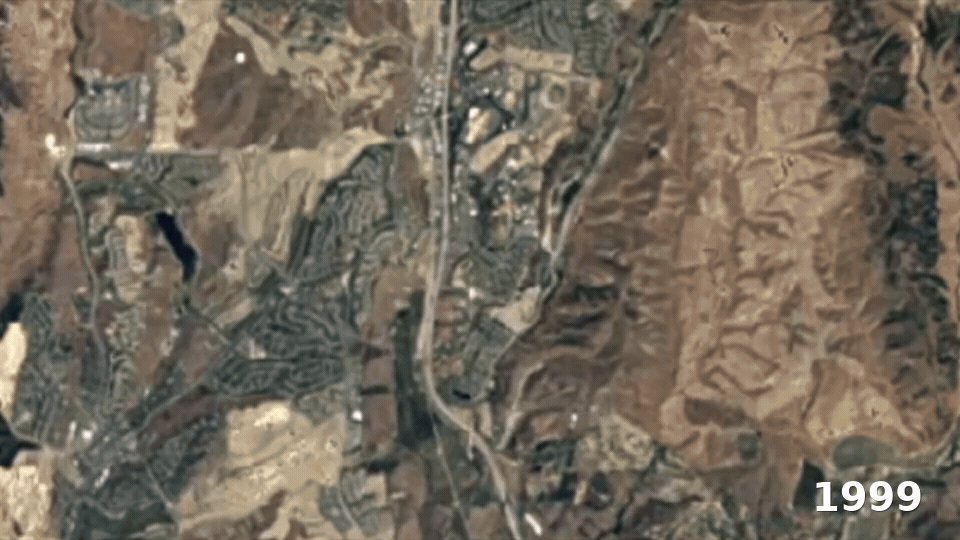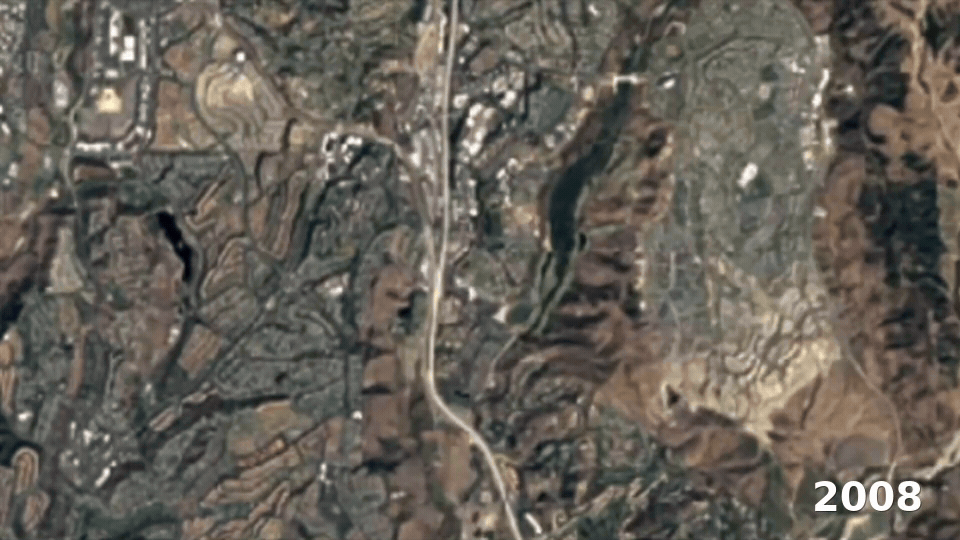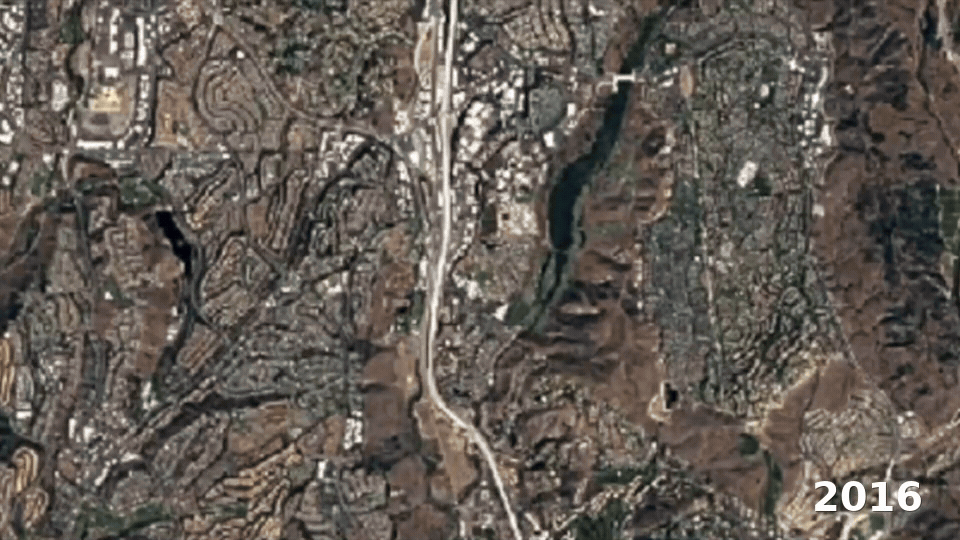
West Coast — Orange County, CA
The Next Chapter Is Being Written in Texas
What the East and West Coasts were in earlier generations, Texas is becoming now. Those earlier growth corridors have matured, and much of the land has already been repriced. For investors who missed those coastal appreciation cycles, the Texas Megaregion offers an opportunity to recognize the same pattern while it is still unfolding—at lower entry prices, with less competition, and before its emerging growth corridors fully mature.